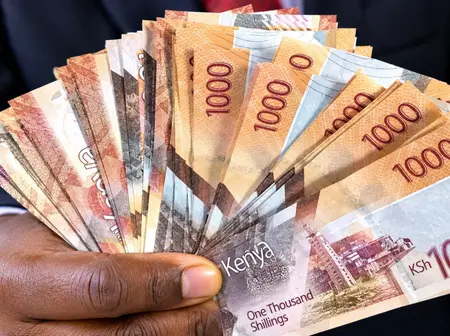
The Kenyan shilling has weakened past Ksh130 against the US dollar, raising questions about whether the local currency is losing the stability it maintained for more than two years.
However, the latest movement may not signal an impending currency crisis, with Central Bank of Kenya (CBK) data showing that the country still has substantial foreign exchange reserves to cushion its economy against external shocks.
In July 2026, CBK Governor Kamau Thugge explained the factors behind the shilling’s prolonged stability, saying, “Indeed, it has been steady since early 2024. It has fluctuated between 120 and 129.”
On Friday, November 20, 2026, CBK’s exchange-rate data placed the US dollar at Ksh130.00, while Bloomberg quoted it at Ksh130.0700. The development marks another breach of the threshold after the shilling briefly weakened beyond it in April before recovering.
One of the strongest indicators of Kenya’s ability to withstand currency pressure is its foreign exchange reserve position.
CBK reported that reserves stood at $13.949 billion (approximately Ksh1.813 trillion) as of November 19, equivalent to 5.6 months of import cover. This remains above the statutory minimum requirement of four months.
However, reserves declined from $14.605 billion (approximately Ksh1.899 trillion) on November 12, representing a reduction of $656 million (approximately Ksh85.3 billion) in one week.
The decline raises questions about Kenya’s foreign currency outflows, including external debt payments, government transactions and possible central bank operations. However, the published figures do not establish that CBK sold dollars to defend the shilling.
Diaspora remittances have also weakened slightly, declining by 1.9 per cent to $430.5 million (approximately Ksh55.9 billion) in October 2026, compared with $438.8 million (approximately Ksh57 billion) in October 2025.
Despite the reduction, Kenya continues to receive billions of dollars annually from citizens working abroad, providing an important source of foreign exchange.
The shilling’s movement is also taking place against changing conditions in international currency markets.
CBK’s November 20 bulletin indicated that the US Dollar Index strengthened by 0.70 per cent during the week ending November 19, potentially adding pressure on emerging-market currencies.
CBK has previously explained that the exchange rate is determined by market forces rather than fixed by the central bank.
“The Central Bank does not set the exchange rate; it is market determined based on supply and demand of foreign exchange,” the institution states on its website.
This means crossing Ksh130 does not automatically indicate that the central bank has lost control of the currency market.
A weaker shilling also has different implications for various sectors. Importers purchasing petroleum, medicines, machinery and industrial raw materials in dollars may face higher costs, while exporters earning foreign currency could receive more shillings when converting their earnings.
The government could also require more local currency to service external debt denominated in dollars.
The debate over the shilling’s stability is not entirely new. In October 2025, IMF officials reportedly questioned whether the currency’s unusually narrow trading range reflected underlying market conditions.
“The IMF were in town two weeks ago, and one of the things they told us is that the exchange rate is too stable,” Ndiritu Muriithi, Kenya Revenue Authority chairman, said.
“I found it strange myself that the IMF would say the exchange rate is too stable.”
Thugge previously attributed the shilling’s stability to foreign currency inflows from diaspora remittances, agricultural exports, foreign investments and development partners.
However, maintaining exchange-rate stability over the long term requires sustained foreign currency earnings to meet Kenya’s import requirements and external financial obligations.
The latest reserve figures suggest that Kenya still has a substantial buffer, although the decline in reserves and remittance inflows warrants attention.
For now, crossing Ksh130 should not automatically be interpreted as a return to the currency instability experienced in earlier years.
The more important indicators will be whether reserves continue declining, whether import cover approaches the statutory minimum and whether demand for dollars persistently exceeds available supply.
Until those indicators show sustained deterioration, the Ksh130 threshold alone may say more about market psychology than the actual health of Kenya’s foreign exchange position.
Leave a Reply