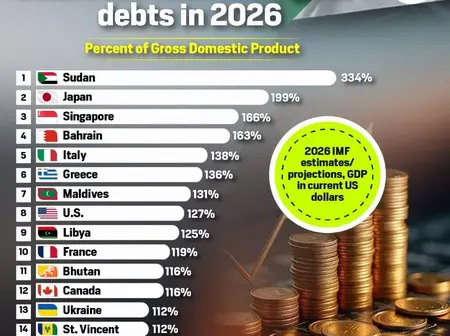
Recent IMF estimates and projections measuring debt as a percentage of gross domestic product in current US dollars reveal stark global fiscal pressures, with several nations carrying debt burdens exceeding the size of their entire economies.
At the top of the global ranking, Sudan records the highest debt-to-GDP ratio at a staggering 334 per cent. Japan follows significantly behind in second place at 199 per cent, while Singapore rounds out the top three nations with a debt ratio of 166 per cent.
The data highlights widespread sovereign debt challenges across multiple continents. Bahrain stands at 14th with 163 per cent, followed by European economies such as Italy at 138 per cent and Greece at 136 per cent.
Further down the list, the Maldives registers 131 percent, and the United States stands at 127 per cent. Libya follows closely at 125 per cent, while France records 119 per cent.
Bhutan and Canada share identical ratios at 116 percent, ahead of Ukraine and St. Vincent at 112 per cent, and Cabo Verde and Belgium at 110 per cent.
As the rankings progress into double-digit percentages of economic output, China registers 104 per cent and the United Kingdom records 102 per cent.
Both Bolivia and Dominica sit at 100 per cent, marking the threshold where national debt equals total economic output. Spain follows at 98 per cent, Brazil at 97 per cent, and Sri Lanka at 95 per cent.
Barbados records 94 per cent, while Mozambique and Finland tie at 91 per cent. Mauritius stands at 88 percent, Tunisia at 86 per cent, and Portugal and Suriname conclude the recorded rankings at 85 per cent.
These IMF figures underscore the heavy fiscal liabilities managed by governments worldwide as economic conditions evolve.
Leave a Reply