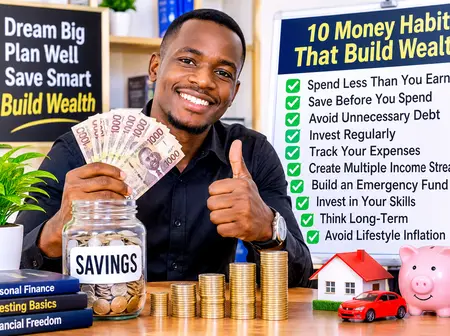
Many people dream of becoming wealthy, buying their own homes, starting successful businesses and living without constantly worrying about money. However, building wealth is not always about earning a huge salary or coming from a rich family. Sometimes, the difference between someone who struggles financially and someone who gradually becomes wealthy comes down to the way they handle the money they receive.
You may earn KSh 20,000 a month while another person earns KSh 100,000. Surprisingly, the person earning less might eventually build more wealth if they develop better financial habits.
The truth is that wealth does not usually appear overnight. It grows through small financial decisions that are repeated consistently. What you do with your money today can have a significant impact on your financial position several years from now.
Here are ten important money habits that can help you accumulate wealth over time.
One of the most important principles of building wealth is learning to live below your income.
It sounds simple, but many people struggle with it. Whenever their salaries increase, their expenses also increase. Someone who previously survived on KSh 20,000 may start spending KSh 35,000 after their salary rises to KSh 40,000.
This creates a situation where earning more money does not necessarily improve their financial position.
Instead of increasing your lifestyle every time you receive additional income, consider maintaining your current spending habits and directing the extra money towards savings or investments.
For example, if you earn KSh 30,000 monthly, you could aim to save KSh 3,000 to KSh 5,000, depending on your responsibilities.
The amount might appear small, but consistency makes a difference.
Many people receive their salaries and immediately begin paying rent, shopping, clearing debts and supporting relatives. By the time they finish, there is almost nothing left.
A better approach is to save a portion of your income immediately after receiving it.
Think of savings as one of your essential monthly expenses.
For instance, if you receive KSh 40,000, you could transfer KSh 4,000 into a separate savings account before spending the remaining amount.
This habit helps you avoid the common mistake of saving whatever remains at the end of the month.
Sometimes, nothing remains.
Paying yourself first ensures that you are consistently building something for your future.
One financial mistake that quietly destroys wealth is spending money to maintain an image.
Some people purchase expensive phones, clothes, shoes and vehicles simply because they want others to believe they are financially successful.
Unfortunately, looking wealthy and being wealthy are two different things.
Someone driving an expensive vehicle might be struggling with loan repayments, while another person using an ordinary phone might own profitable investments and have substantial savings.
Before purchasing something expensive, ask yourself whether you genuinely need it or whether you are simply trying to impress people.
There is nothing wrong with enjoying your money. However, your desire to impress others should not prevent you from achieving financial independence.
Saving money is important, but investing can help your wealth grow over time.
Money kept in an ordinary savings account may lose purchasing power when inflation increases. Investments, depending on their performance and risks, can provide opportunities for growth.
There are several investment options worth learning about, including:
You do not need millions of shillings to begin learning about investments.
For example, someone who consistently invests KSh 2,000 every month is developing a habit that can become increasingly valuable as their income grows.
However, remember that investments carry different levels of risk. Understand an investment before committing your money, and avoid opportunities promising guaranteed extraordinary returns.
Borrowing money can sometimes help someone grow financially, especially when the money is used for a productive business or investment.
However, borrowing to finance unnecessary lifestyles can create serious financial problems.
Imagine borrowing KSh 15,000 to purchase an expensive phone when your current phone is still working perfectly.
You now have an additional financial obligation without creating anything that generates income.
Before taking any loan, consider three questions:
Be particularly careful with mobile loans that carry high interest rates and additional fees.
The goal should be to use borrowing wisely rather than allowing debt to control your income.
Depending entirely on one source of income can make financial progress difficult.
If your salary stops, your entire financial situation may be affected.
This is why developing additional income streams can be an important part of building wealth.
For example, someone employed as a teacher might also operate a poultry business, write articles online, sell agricultural products or invest in a small enterprise.
The advantage is that additional income can provide money for savings and investments without necessarily interfering with the primary source of income.
However, do not rush into every business opportunity you encounter.
Start with something you understand, calculate the costs and potential profits, and grow gradually.
A small business generating KSh 5,000 in monthly profit can become a meaningful additional income source when managed properly.
You cannot manage your finances effectively if you do not understand where your money goes.
Many people complain about having insufficient income, yet they cannot clearly explain how they spend their salaries.
Small expenses can accumulate into surprisingly large amounts.
For example:
This does not mean you should stop enjoying life.
Instead, develop the habit of recording your expenses.
You can use a notebook, spreadsheet or mobile application.
At the end of every month, review your spending and identify areas where you can make improvements.
Sometimes, wealth accumulation begins by discovering where your money has been disappearing.
Unexpected situations can destroy years of financial progress.
You might suddenly become sick, lose your job, experience business losses or need urgent repairs at home.
Without emergency savings, you may be forced to borrow money or sell valuable assets.
An emergency fund provides financial protection against such situations.
Start by setting aside a small amount every month.
Your first target could be KSh 10,000. After achieving that, gradually work towards saving enough to cover three to six months of essential living expenses.
Keep this money somewhere safe and accessible, separate from your everyday spending money.
An emergency fund is not primarily designed to make you rich. It helps prevent unexpected problems from making you financially unstable.
One of the most valuable investments you can make is investing in yourself.
Your education, professional skills and ability to solve problems can influence how much money you earn throughout your life.
Consider learning skills that have opportunities in the modern economy.
These might include:
You do not always need expensive courses to acquire useful knowledge. There are free educational resources available online.
The important thing is to learn skills that you can eventually use to generate income.
Sometimes, improving your ability to earn money can produce greater long-term financial benefits than simply trying to reduce your expenses.
One reason people lose money is their desire to become wealthy within a very short period.
They jump into questionable investment schemes, gambling, unverified online opportunities and businesses they barely understand.
Unfortunately, the promise of making KSh 100,000 from an investment of KSh 5,000 within a few weeks can be difficult to resist.
However, genuine wealth creation usually requires patience, discipline and informed decisions.
Instead of looking for shortcuts, establish financial goals.
You might decide that within five years, you want to own a profitable business, accumulate KSh 300,000 in investments or purchase a piece of land.
Break these ambitions into smaller monthly targets.
Progress may initially appear slow, but consistent action can produce meaningful results.
Becoming wealthy is not necessarily about how much money you receive every month. It is also about how much you retain, how wisely you invest and how effectively you use your resources.
Someone earning KSh 25,000 who saves and invests consistently may gradually build a stronger financial foundation than someone earning KSh 100,000 but spending everything.
You do not need to introduce all ten habits into your life tomorrow.
Start with three: spend less than you earn, save before spending and avoid unnecessary debt.
Once these become part of your lifestyle, introduce other habits gradually.
Remember, financial success is not always determined by one big decision. Sometimes, it is the result of hundreds of small decisions made correctly over several years.
A question worth thinking about: If you started saving and investing a small amount of money every month today, where could you be financially five years from now?